A personal platform for building and paper-trading systematic strategies, designed so that research results can be trusted: the architecture makes common sources of silent error — mutated history, bypassed risk checks, lookahead bias — structurally impossible rather than merely discouraged.
Architecture
Results
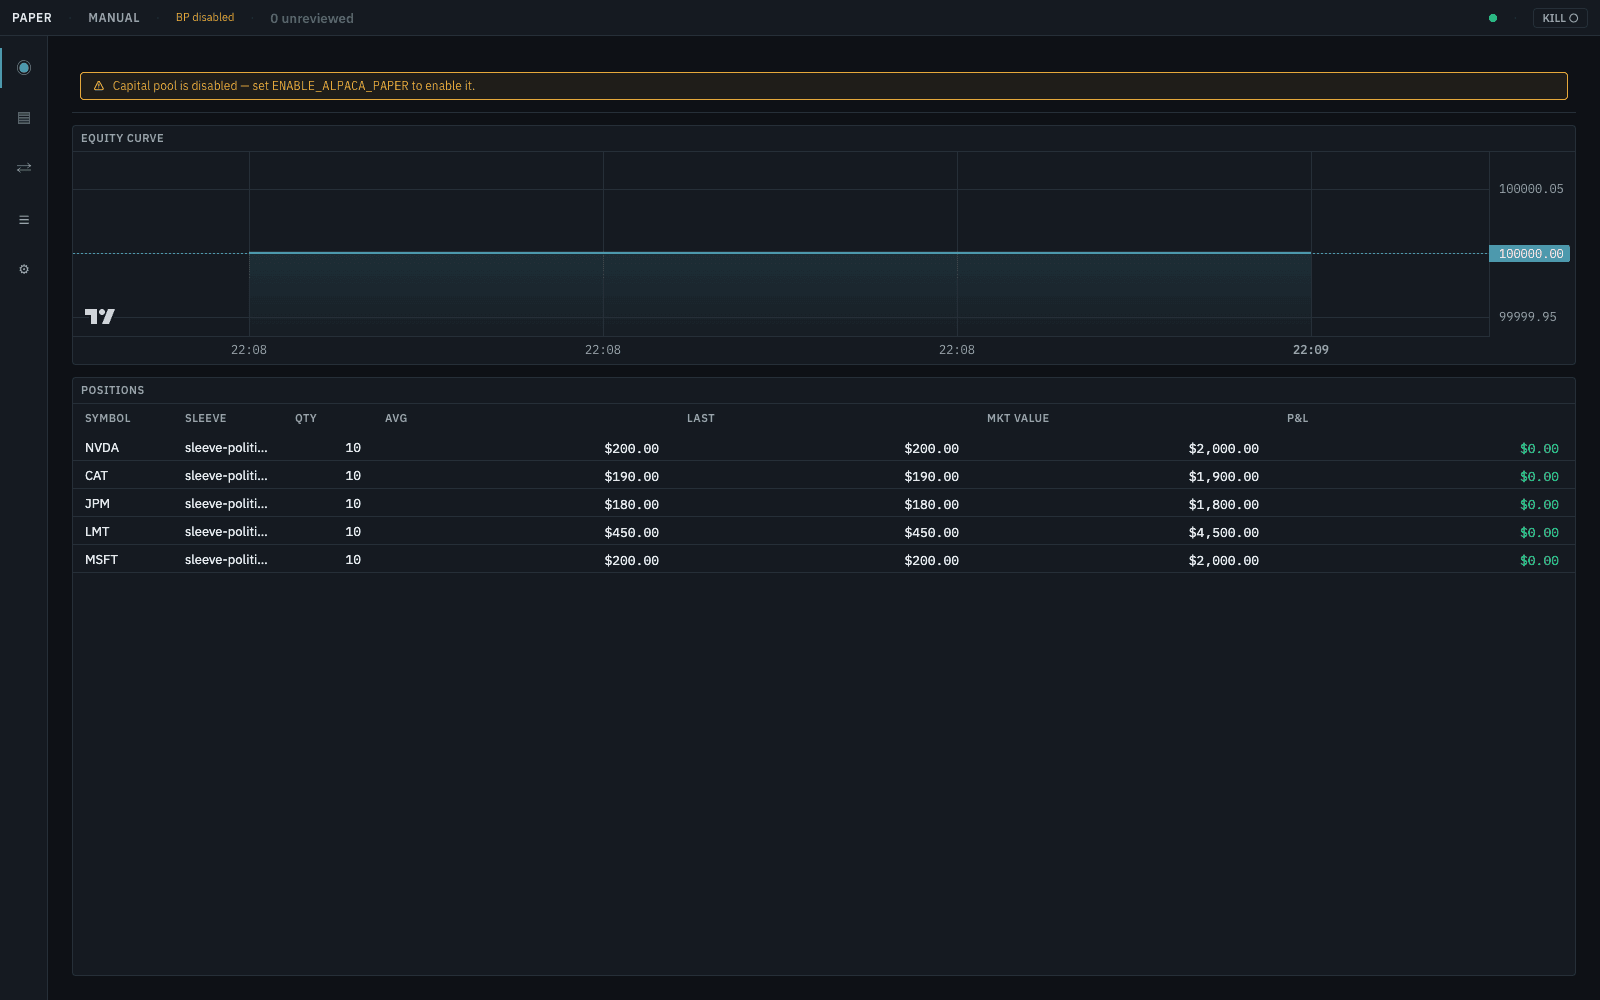
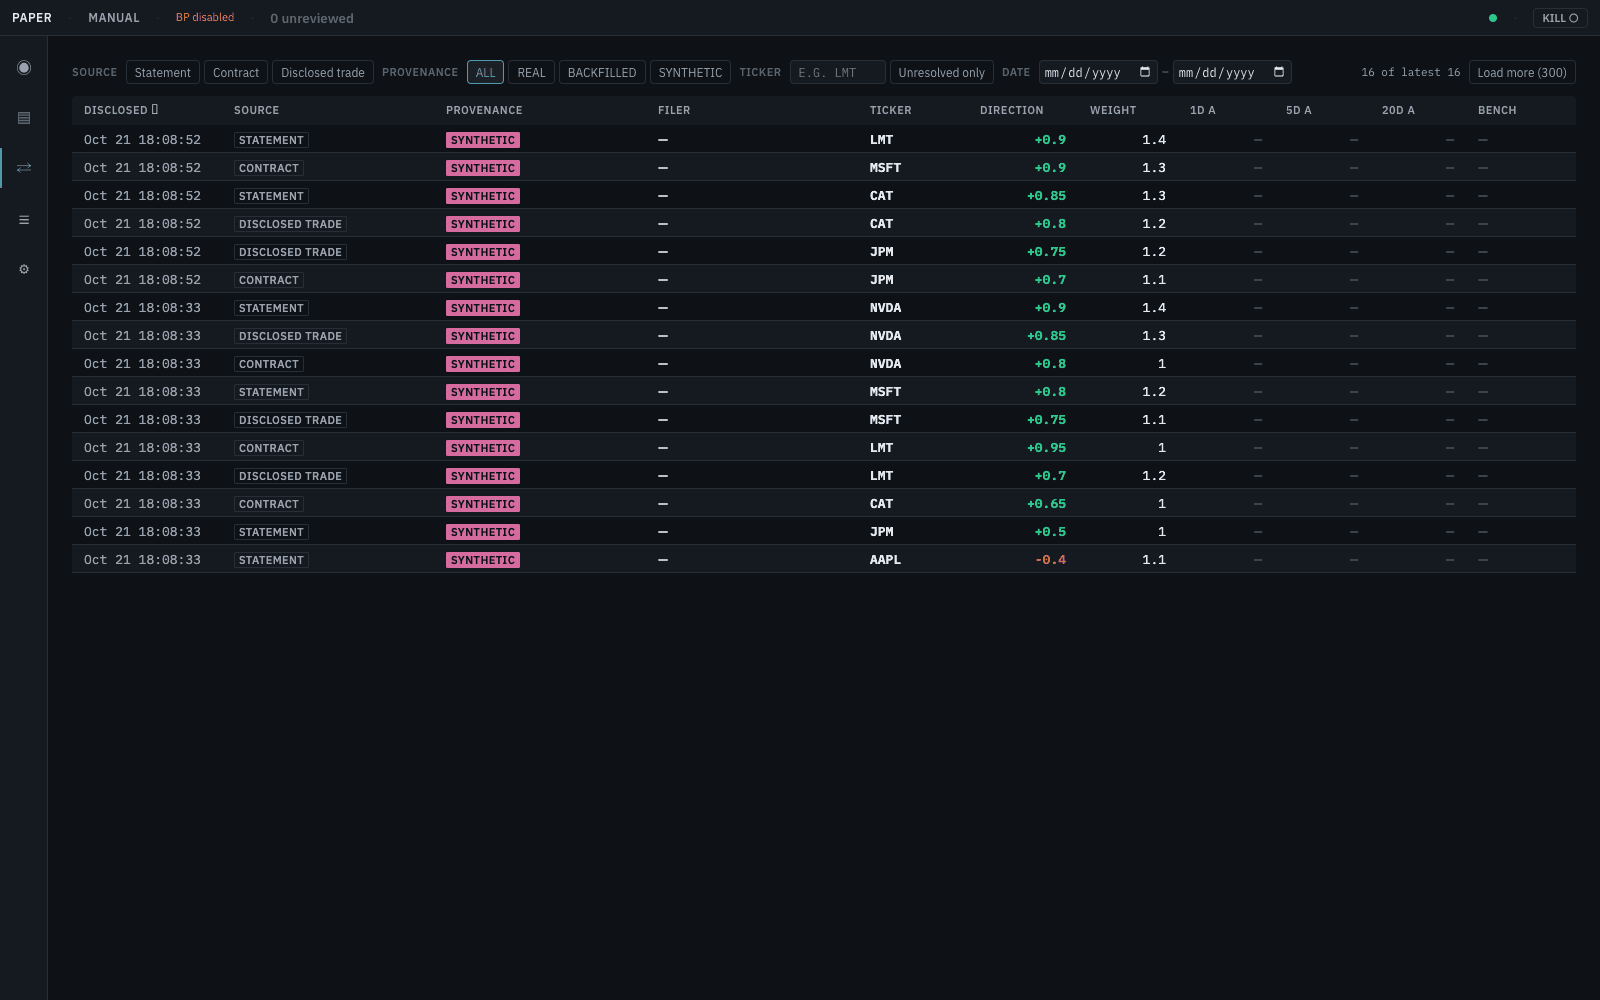
Operations console — demo environment, synthetic signalsSignal feed — the provenance guard labels synthetic data and blocks it from real-broker decisions
Key Contributions
Append-only event log as the system of record; current state is derived as projections, never stored as mutable truth
Non-bypassable risk gate boundary in front of every order
Point-in-time historical backfill program with explicit lookahead-bias controls for building training datasets
Hexagonal ports-and-adapters architecture: adding a strategy or data source is one module plus one registration
React operations console over a Python / FastAPI / Postgres backend